· ReadyStack
Worked example
Real numbers from this tool, line by line.
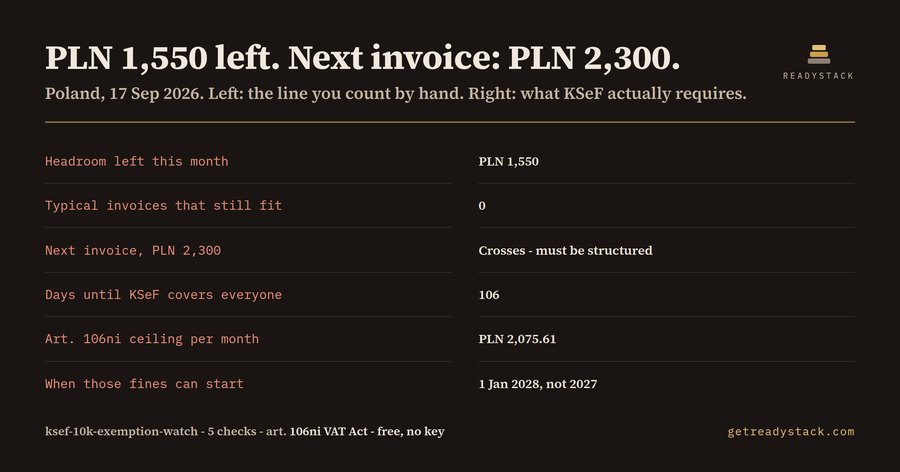
PLN 1,550. That is all the headroom a Warsaw micro-entrepreneur had left on 17 September 2026, and the invoice already sitting on their desk was PLN 2,300. That invoice does not just push them over a threshold next month. Under the Polish rules it must itself be issued as a structured invoice in KSeF, because the exemption dies on the invoice that crosses the line.
Poland's National e-Invoice System went mandatory in waves: companies with 2025 sales above PLN 200 million on 1 February 2026, everyone else on 1 April 2026. Only the smallest are still outside - monthly gross B2B invoicing at or under PLN 10,000 - and only until 31 December 2026. On 1 January 2027 KSeF covers everyone, with no grace period.
The trap is not the end date. It is the cliff inside every month. The exemption is measured per calendar month on gross invoiced sales, and you lose it starting with the invoice that breaks PLN 10,000 - not from the following month, and not after a warning. Cross it once and the obligation is permanent; you cannot drop back under the limit in a quiet month and return to paper.
Run the September figures through it and the arithmetic is unforgiving. PLN 8,450 already invoiced this month leaves PLN 1,550 of headroom. A typical invoice of PLN 1,850 no longer fits at all, so the count of invoices that still fit is zero. The next invoice, at PLN 2,300, crosses. The verdict is not 'you will need KSeF in January' - it is that this invoice must be structured today.
The second number is the exposure. Article 106ni lets the head of the tax office fine a taxpayer who invoices outside KSeF despite the obligation: up to 100% of the VAT shown, or up to 18.7% of the total due where no VAT is shown. Six invoices a month at PLN 1,850 gross is PLN 11,100, and at 23% VAT the tax inside that is PLN 2,075.61. That is the monthly statutory ceiling, every month, for as long as the invoices keep going out the old way.
The two percentages are not alternatives. At 23%, the VAT fraction of a gross amount is 23/123, or 18.699% - the 18.7% branch is the standard-rate fraction written into the statute so that zero-rated invoices cannot escape the sanction.
This is also the point where a free chatbot will hand you a wrong answer with total confidence. Ask one today and it will tell you Polish KSeF sanctions begin on 1 January 2027, because that is what the statute said and what every guide published through mid-2026 repeated. On 16 September 2026 the Ministry of Finance announced that the Article 106ni administrative sanctions are deferred to 1 January 2028. The obligation was not deferred. The exemption end date was not deferred. Only the fines moved, and a tool that still prints 2027 is telling you to panic about the wrong thing while missing the thing that actually binds.
Change the status to a company caught by the April wave and the headroom reads PLN 0 - the exemption never applied - with PLN 1,047.15 of monthly exposure on four invoices of PLN 1,400. Move to 1 December 2026 on a zero-rated exporter and it flips to still exempt, five typical invoices fit, 31 days left. Same five checks, three verdicts, because the rule turns on your turnover, your rate and today's date.
The calculator is free and runs in the browser - headroom, the crossing invoice, the wave date, days remaining and the statutory ceiling, with no key and no limit. The licence key adds a different axis, not a bigger number: a .csv export of the month-by-month ledger and a monthly alarm that re-checks the limit on the 1st, so the month after this one does not surprise you the same way.
Questions people ask
What does KSeF 10k Exemption Watch actually do?
It takes the gross B2B invoices you have already issued this month and tells you how much of the PLN 10,000 exemption is left, whether your next invoice crosses it, and the date from which you must issue in KSeF. It also computes the Article 106ni maximum exposure on invoices you keep issuing outside the system.
Who is this for?
Polish micro-entrepreneurs still invoicing on paper under the PLN 10,000 monthly exemption, and foreign companies VAT-registered in Poland whose Polish turnover is small enough that nobody told them a wave applies. Also for accounting offices watching dozens of small clients drift toward the limit.
Why will a free chatbot not answer this?
Because the timetable moved twice. Chatbots still repeat that KSeF sanctions begin 1 January 2027; the Ministry of Finance announced on 16 September 2026 that they are deferred to 1 January 2028. They also miss the sharpest rule: you lose the exemption on the invoice that crosses PLN 10,000, not the following month.
What is free and what needs the key?
Every number is free, forever, with no key and no limit: headroom, the crossing invoice, your wave date, days remaining and the statutory maximum. The $60 licence key adds two things on a different axis - a .csv export of your month-by-month ledger, and a monthly alarm that re-checks your headroom on the 1st.
What would this cost if a person did it?
Polish tax advisers quote PLN 350 to 599 net per hour for consultations, and written opinions start at about PLN 1,999. A single hour spent asking which KSeF wave you fall into costs several times the price of this extension, and you would have to ask again every time the ministry moves a date.
Ask about this tool
One question, answered by the person who built it. Your email only if you want the answer sent.